

Last week, struggling discount retailer Dollar General (DG - $80.41) reported its financial results for Q2 2024 and materially lowered its EPS guidance for the current year.
The stock got hammered and ended up trading -32% lower on the day. Ouch!
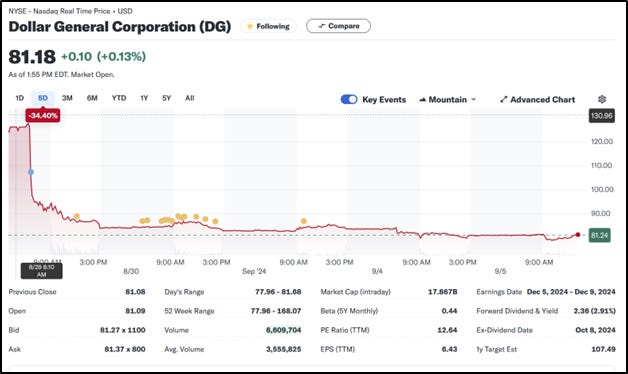
The company’s lowered top-line guidance was relatively benign (approximately -100 Bps vs. previous). But, the bottom-line revision was massively lower (FY EPS $5.50 to $6.20 vs. the previous guidance range of $6.80 to $7.55).
The bottom-line revision is even worse when considering the company had previously earmarked $0.50 of incremental EPS pressure via higher bonus expense this year that would no longer be a profitability headwind.
Again, that’s quite an EPS revision for such a subtle lowering of top-line guidance. But, then again, the company has a track record of issuing aggressive annual EPS guidance at the start of the year… only to materially lower that EPS guidance over the course of the year.
But, here’s what fascinates me. During last week’s quarterly earnings conference call, CEO Todd Vasos said the following at various points of the call…
“We fundamentally don’t believe at all that the model is structurally challenged.”
“Our new store productivity as well as our strong returns in new stores continue to serve us well.”
And then, finally he offered the following…
“We still have a long runway for new store opportunities with high returns.”
Wow! Talk about not seeing the forest through the trees!
Take a look at the following trailing 4-quarter EBIT% chart for DG…
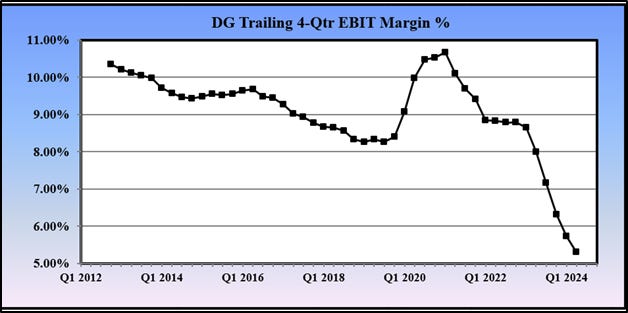
It doesn’t take a seasoned equity research analyst to discern that the company’s business model is ABSOLUTELY structurally challenged. Gosh, it could be argued that DG’s business model has been structurally challenged for over a decade (save for a brief respite during the pandemic).
I’m being somewhat facetious. But, what retail executive looks at the above profitability chart and thinks that the company needs to continue to aggressively open more stores? You have to be “grade A” delusional to think that DG needs additional stores prior to stemming the large-scale profitability decline that has plagued the company for the better part of a decade (and, especially since the end of pandemic year #1).
Dollar stores enjoyed a nice run over the course of the past two decades. The sub-sector carved out a nice niche and took market share from big box discounters and grocery stores… at EBIT margins that were more than 2X higher.
That higher level of profitability encouraged dollar stores to over-expand and their margins have precipitously declined. Gosh, Family Dollar even loses money (when allocated half of DLTR’s unallocated corporate expense which is not reflected in the chart below).
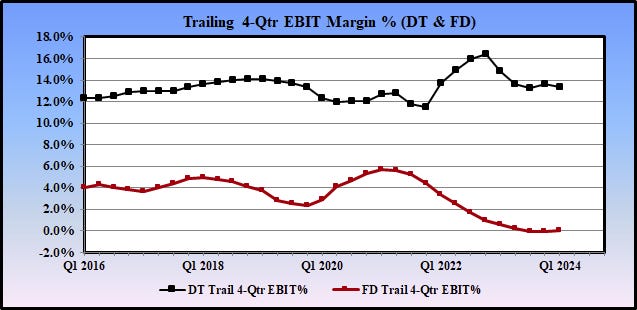
The bottom-line is that DG grew its store count +79% and its square footage +84% in the decade ending in FY 2023 (i.e., the stores got larger over time). Continuing to grow its store base (+730 new store openings this fiscal year) is only managerial malpractice to the highest degree.
Instead, what dollar stores need is to find the next layer of innovation that will differentiate the model. Because, the path dollar stores are on today is a path towards extinction that will only be hastened by the continued, ill-advised store growth.
I wonder if WMT upping their game and labor inflationary pressures disproportionately impacting their per-store economics just permanently ruined the model.
Agreed here. Both DG and DLTR are also seeing ballooning capex. That plus the structural pressures on cash generation suggests they are going to remain quite levered, limiting their flexibility.